Allowable expenses for sole traders are business costs you deduct from your income before working out your taxable profit. HMRC’s core principle is that a cost must be incurred “wholly and exclusively” for the purposes of the trade, profession or vocation. If a cost has both business and private use, only the business part may be allowable, where it can be clearly separated.
This guide covers the most common expenses, the figures for 2026/27 and what records to keep.
What are allowable expenses?
Allowable expenses are business costs that you can deduct from your self-employed income when working out your taxable profit.
For example, if your business income is £40,000 and you have £6,000 of allowable business expenses, your profit would be £34,000. Tax and National Insurance are then worked out on that.
This does not mean every payment from your bank account is automatically deductible. The expense must be related to your business, and you should keep records to support the claim.
The main HMRC rule: business use only
Ask one question: was the cost genuinely for your business?
If yes, it may be allowable. If the cost was personal, it usually is not. If it was partly business and partly personal, you may only be able to claim the business part.
For example, if you use your phone for both business and personal calls, claim only the business proportion of the bill. Everyday clothes that you also wear outside work are usually not allowable just because you wear them while working.
The more clearly you can show what the cost was, why it was paid and how it relates to your business, the easier it is to defend the claim.
Common sole trader expenses
HMRC lists several common categories of allowable expenses for self-employed people, including office costs, travel costs, clothing expenses, staff costs, stock or raw materials, financial costs and business premises costs. Its guidance on expenses if you’re self-employed has the full list.
Below are the categories most relevant to sole traders.
1. Office costs
You may be able to claim costs such as:
- stationery
- printing
- postage
- business phone bills
- business software
- computer software used for work
- small office supplies
For example, if you pay for accounting software, invoicing software, design software or another digital tool that you use for your business, that cost may be an allowable expense.
If something is used partly for personal reasons, such as a phone or internet connection, claim only the business-use proportion.
2. Travel costs
Sole traders may be able to claim travel costs when the journey is for business.
This may include:
- fuel for business journeys
- parking for business trips
- train fares
- bus fares
- taxi fares for business journeys
- vehicle costs where relevant
Some travel costs are not allowable. You cannot claim non-business travel, fines or penalty charges, or normal travel between home and work.
A builder travelling from one client site to another has a business journey. A sole trader driving for a personal errand does not.
If you use a car, van or motorcycle for business, you can use simplified expenses and claim a flat rate for each business mile instead of working out actual running costs. The simplified mileage rates are:
| Vehicle | 2026/27 | 2025/26 |
|---|---|---|
| Car or van, first 10,000 business miles | 55p a mile | 45p a mile |
| Car or van, over 10,000 business miles | 25p a mile | 25p a mile |
| Motorcycle | 24p a mile | 24p a mile |
Your 2025/26 tax return, due by 31 January 2027, uses the 2025/26 rates. For the full rules, read our guide to sole trader mileage allowance.
3. Clothing expenses
Clothing is one of the areas where sole traders often get confused.
You may be able to claim for:
- uniforms
- protective clothing needed for work
- costumes for actors or entertainers
But you usually cannot claim for normal everyday clothing, even if you wear it while working.
For example, steel toe-cap boots or protective workwear may be allowable for a tradesperson. A normal pair of jeans, trainers or a jacket would usually not be allowable just because you wear them to meet clients.
The key question is whether the clothing is specifically required for the business, or whether it is ordinary clothing with a private use as well.
4. Stock, materials and goods for resale
If your business sells goods, makes products or uses materials to deliver work, you may be able to claim the cost of stock and raw materials.
This may include:
- goods bought for resale
- raw materials
- parts used in customer work
- direct production costs
- packaging used for products
For example, a sole trader who makes handmade products may be able to claim the cost of materials used to make those products. A tradesperson may be able to claim materials bought for a customer job.
5. Staff and subcontractor costs
Some sole traders work alone, but others pay subcontractors, freelancers or employees.
HMRC says self-employed people may be able to claim allowable business expenses for costs such as employee salaries, bonuses, pensions, benefits, agency fees, subcontractors, employer’s National Insurance and training courses related to the business. You cannot claim personal domestic help such as nannies or carers.
6. Legal, financial and professional costs
Professional costs may also be allowable when they are for business reasons.
This can include:
- accountancy fees
- legal advice for business matters
- professional indemnity insurance
- business bank charges
- business insurance
For example, paying an accountant to help with your Self Assessment tax return may be allowable. Paying a solicitor for a personal matter would not usually be a business expense.
7. Business premises costs
If you rent or operate from business premises, you may be able to claim costs such as:
- rent for business premises
- business rates
- utility bills
- property insurance
- security
- heating and lighting
8. Working from home expenses
Many sole traders work from home at least some of the time.
There are two broad ways to claim:
- calculate the actual business proportion of your home costs, or
- use simplified expenses, where HMRC allows it.
Simplified expenses let you use flat rates instead of calculating exact business costs. They are optional, so you can choose whether they suit your business. You can only use the working from home flat rate if you work 25 hours or more a month from home. The flat rates for the extra household costs are:
| Hours you work from home each month | Flat rate per month |
|---|---|
| 25 to 50 | £10 |
| 51 to 100 | £18 |
| 101 or more | £26 |
If you claim actual costs instead, claim only the part of your household bills that is used for business, and be able to show how you worked it out. Don’t simply claim household bills without a clear basis.
9. Equipment, tools and big purchases
Under the cash basis, which has been the default for sole traders since 2024/25, most equipment and tools you buy for the business are simply an expense, claimed in the year you pay for them.
Cars are the exception. You claim for a car through capital allowances, or you use the mileage rates above instead of claiming actual costs. You can’t do both for the same vehicle.
Capital allowances are a separate set of rules for big purchases, and the annual investment allowance is part of them. If you are buying something expensive and you are not sure which rules apply, read HMRC’s guidance on capital allowances or ask an accountant.
If you use an item for both business and private reasons, claim only the business share.
The £1,000 trading allowance
Instead of claiming your actual expenses, you can claim a £1,000 trading allowance. You can use the allowance or claim your actual expenses, but not both. It only makes sense if your actual expenses are less than £1,000.
Expenses sole traders usually cannot claim
Common non-allowable costs include:
- personal expenses
- everyday clothing
- non-business travel
- normal travel between home and work
- fines and penalties
- personal food and drink in normal circumstances (reasonable meals on overnight business trips or unusual journeys can be allowable)
- costs where the business and private part cannot be separated
- domestic help such as childcare or nannies
A useful rule of thumb: if the cost would still exist even if you did not run the business, it may not be fully allowable.
Do you need receipts for sole trader expenses?
Yes, you should keep evidence of your business expenses.
HMRC says self-employed people need to keep records of all sales and income, all business expenses, VAT records if registered for VAT, PAYE records if they employ people, and records about personal income.
You do not usually need to send proof of expenses when submitting your Self Assessment tax return, but you should keep records so you can show them to HMRC if asked.
Good records may include:
- receipts
- invoices
- bank statements
- mileage logs
- supplier bills
- software subscription invoices
- notes explaining business use
- records of how you calculated business/private splits
HMRC says self-employed people must keep their records for at least 5 years after the 31 January submission deadline of the relevant tax year.
Small costs like parking, postage and software subscriptions are the ones that go missing, so photograph the receipt when you get it. If Making Tax Digital applies to you, you also have to keep your records digitally. It is already live for qualifying income over £50,000 and starts for income over £30,000 from April 2027.
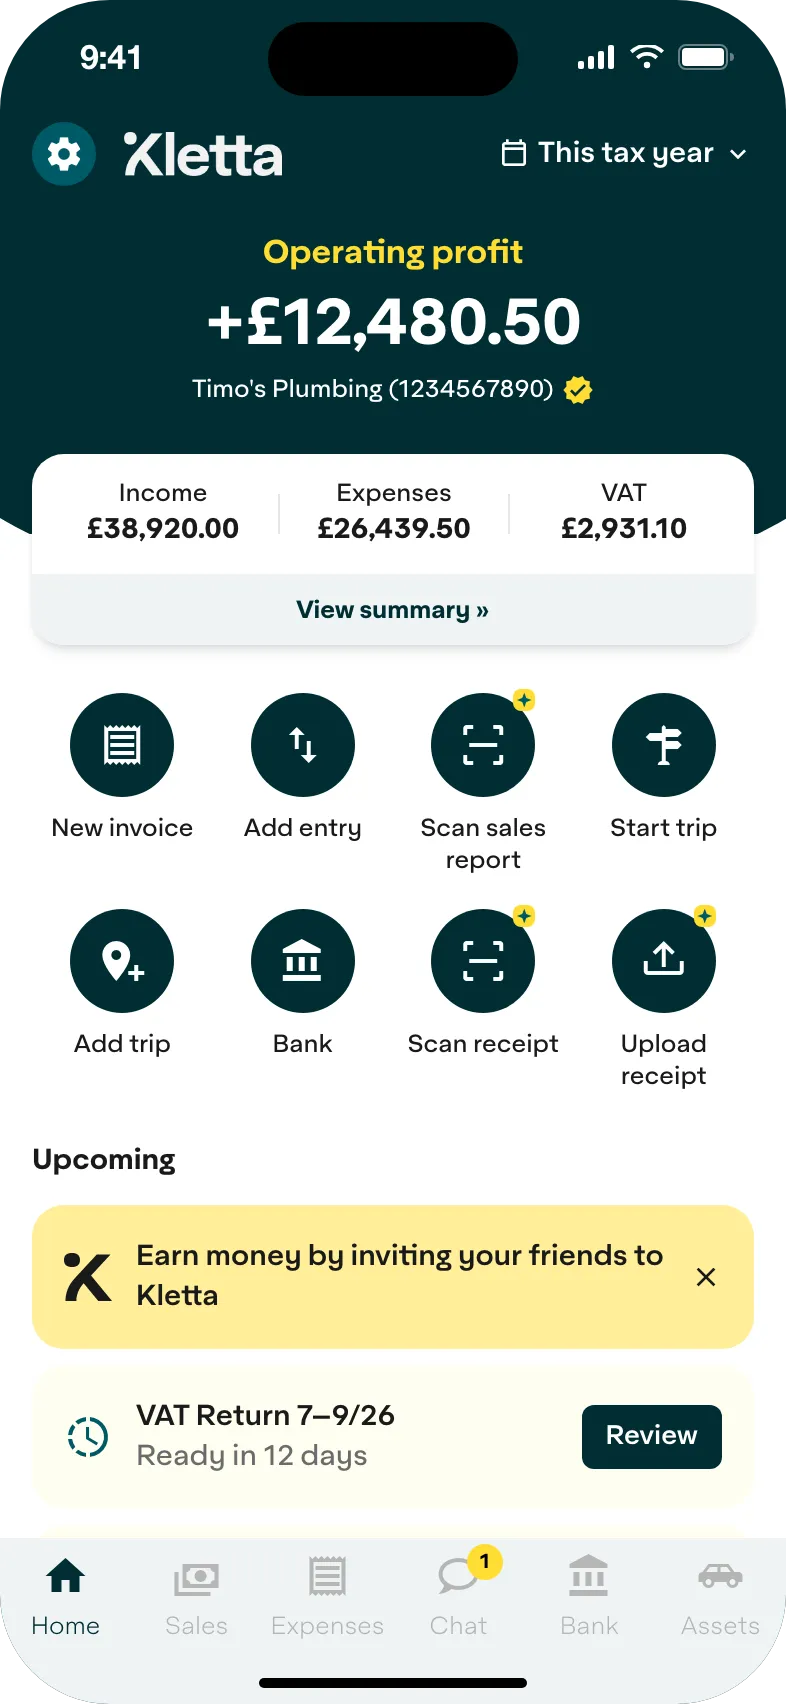
In Kletta you can scan receipts, categorise expenses and track business mileage from your phone.
Three questions to ask before you claim
- Was this cost for my business?
- Can I prove it?
- Have I kept a clear record of it?
If the answer to all three is yes, the expense may be allowable. If the cost is personal, mixed-use or unclear, check HMRC guidance or speak to a professional.
Kletta is HMRC-recognised Making Tax Digital software for sole traders. Keeping your books and building your tax return is free. You pay only when you’re ready to send to HMRC (see pricing). Not in Making Tax Digital yet? Get Kletta Duo free until your first Making Tax Digital deadline.